The Mike Brown Group breaks down what the November 3, 2026 midterm elections, in which Democrats won control of both the U.S. House and Senate, mean for the Boise and Treasure Valley housing market, from mortgage rates and home prices to the decision to buy or sell this winter. With the 30-year fixed rate holding above 7% and divided government making sweeping federal tax or housing changes less likely, local inventory, pricing and timing remain the biggest factors for Ada and Canyon county buyers and sellers heading into 2027.
The Big Picture

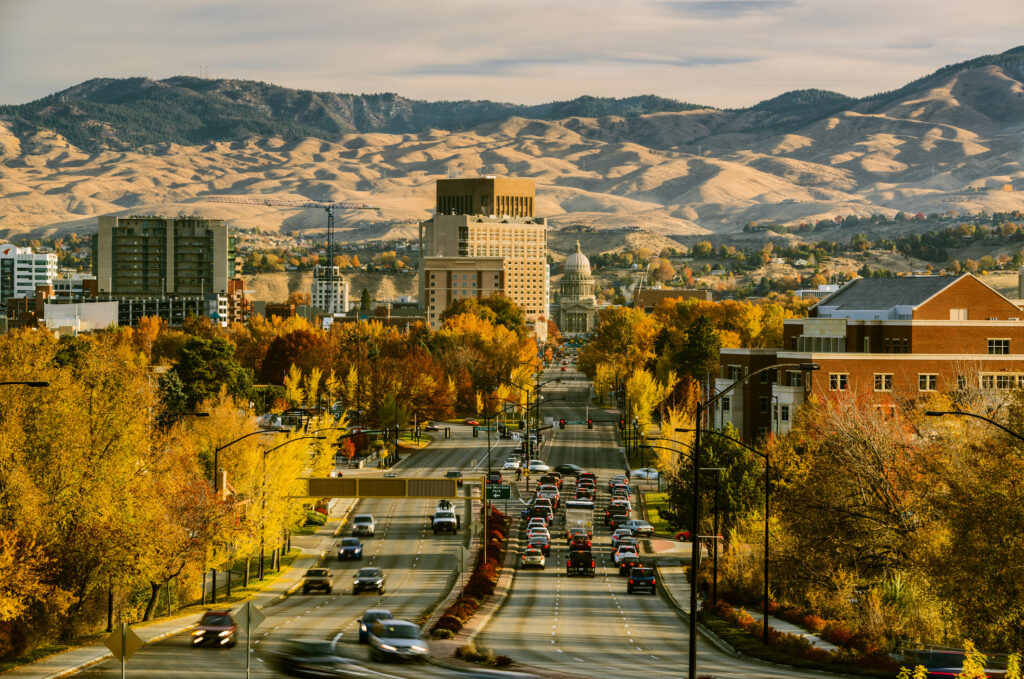
The 2026 midterms are over, and the results reshuffle the balance of power in Washington just as the Treasure Valley housing market heads into its usual winter slowdown. If you’re buying, selling, or just watching from the sidelines, the question on everyone’s mind is the same: what does a new Congress actually mean for mortgage rates, home prices, and the decision to move this winter?
Here’s the short version, with the details below. Democrats flipped control of both the House and the Senate, ending a run of unified Republican control of Congress. Mortgage rates sat at 7.26% for a 30-year fixed loan as of November 4, 2026, according to Bankrate’s national survey, little changed from where they stood heading into Election Day. And the single biggest factor shaping the Treasure Valley market right now — inventory, pricing, and how fast homes move — is still mostly local, not national.
What Changed in Washington
Democrats won control of both chambers of Congress in the November 3, 2026 midterms, CBS News projected — a reversal from the Republican-held Senate and House that existed going into Election Day. In the House, Democrats are on pace to pick up roughly 40 seats, moving from 214 seats before the election to an estimated 256. In the Senate, Democrats flipped the chamber from a 53-47 Republican majority, picking up seats that included Texas — where Democrat James Talarico defeated Republican Ken Paxton — while holding competitive seats like Georgia, where Senator Jon Ossoff won reelection.
The practical result: for the next two years, a Democratic-controlled Congress shares power with a Republican White House — a return to divided government after a period of one-party control. Idaho itself remains solidly Republican at the state level, so local land use, permitting, and property tax policy in the Treasure Valley aren’t expected to shift because of the national result. What changes is the backdrop in D.C.: the pace of federal legislation, budget fights, and how aggressively Washington pushes new tax or housing policy over the next two years.
Interest Rates: What the Election Changes (and What It Doesn’t)
Mortgage rates don’t move because a party wins Congress — they move on the Federal Reserve’s actions, inflation data, and how investors price in both. The Fed held its benchmark rate steady at its October meeting, and as of November 4, 2026, the average 30-year fixed mortgage rate stood at 7.26%, essentially flat compared with where it was before the election.
Where the election does matter is in how markets read the next two years. Several mortgage analysts tied their outlook directly to the midterm result: one described the market’s reaction to expected Washington gridlock as favorable, noting that divided government typically means less dramatic deficit spending and, in turn, less upward pressure on the Treasury yields that mortgage rates track. On the other side, inflation is still running around 3.7%, and at least one analyst flagged the possibility of a Fed rate hike rather than a cut before year-end — a reminder that rates could move in either direction depending on the next few inflation and jobs reports.
For context, Freddie Mac’s national weekly survey shows how much rates have already moved this year: its 30-year average sat at 6.55% in mid-July 2026 and 7.18% in its November 5 survey, meaning rates have climbed roughly six-tenths of a point since summer. That swing alone has a bigger effect on a monthly payment than most of what happens in Washington.
Market Certainty: Why Gridlock Isn’t Necessarily Bad News
Divided government has a reputation for gridlock, and gridlock has a reputation for being bad news. For housing, that’s not quite right. Bond markets — which drive mortgage rates — often prefer a divided Congress precisely because it lowers the odds of abrupt policy swings, whether that’s a major new spending package, a tax overhaul, or a sudden change to housing-related programs.
That’s a meaningful distinction for anyone trying to time a purchase or a listing around “what Washington will do.” The honest answer heading into 2027 is: probably not much, at least not quickly. A Congress split between two parties that need to find common ground to pass a budget each year is far more likely to produce continuity than disruption. For buyers and sellers, that argues for making decisions based on local conditions — rates, inventory, and your own timeline — rather than waiting to see how a divided Congress plays out.
What This Means for Buyers
If you’ve been waiting for the election to “fix” interest rates, the data doesn’t support holding out. Rates were essentially unchanged the week of the election and have actually trended higher than they were over the summer. A divided Congress lowers the odds of a sudden rate shock in either direction, which is itself useful information — it means the current rate environment, high 6s to low 7s, is a reasonable planning assumption rather than something to wait out.
Locally, buyers still have more room to negotiate than they did a few years ago. Ada and Canyon counties both saw new listings rise by double digits in the first half of 2026, and months of supply crept up toward 2.5 — not a buyer’s market outright, but a long way from the bidding wars of 2021. That gives buyers leverage to ask for rate buydowns, closing cost credits, or other terms instead of chasing a lower sticker price.
What This Means for Sellers
Political uncertainty isn’t what’s driving buyer hesitation right now — rate-driven payment math is. With the 30-year fixed near 7.26%, pricing a home accurately matters more than it did in a market where almost anything sold. Homes priced to the current market and shown well are still moving quickly: Boise‘s median days on market held at roughly a week through the first half of 2026. Overpriced or dated listings, on the other hand, are sitting and taking price cuts.
The political transition in Washington gives sellers one useful piece of information: don’t expect a rate-driven rush of buyers in the next few months because of the election. A divided Congress makes fast, sweeping policy change less likely, which means the market sellers see today — rate-sensitive buyers, more competition from rising inventory — is a reasonable picture of the market for the next several months, not a temporary dip before something shifts.
The Outlook Heading Into 2027
The 2026 midterms changed who holds power in Washington, but they didn’t change the fundamentals driving the Treasure Valley housing market. Rates will keep responding to inflation data and Fed decisions, not to which party controls Congress. Divided government is more likely to mean policy continuity than disruption, which gives buyers and sellers a reasonably stable backdrop to plan against — even if “stable” still means rates in the 6s and 7s rather than the 3s some buyers remember.
For local market updates as the data comes in from Ada and Canyon counties, Mike Brown Group tracks Boise, Meridian, Nampa, Caldwell, Eagle, Star, and Kuna every quarter. Whether you’re buying, selling, or just keeping an eye on your home’s value, reach out any time to talk through what these numbers mean for your specific situation.
Frequently Asked Questions
Who won control of Congress in the 2026 midterm elections? ▸
Democrats won control of both the U.S. House and Senate in the November 3, 2026 midterms, according to CBS News projections. Starting in January, a Democratic-controlled Congress will share power with a Republican White House.
Do midterm elections change mortgage rates? ▸
Not directly. Mortgage rates move on Federal Reserve policy, inflation data and the Treasury yields investors set, so an election matters mainly through how markets read the next two years of federal policy.
What are mortgage rates after the 2026 midterm elections? ▸
The average 30-year fixed rate was 7.26% as of November 4, 2026, according to Bankrate, and Freddie Mac’s weekly average was 7.18% on November 5. Both were little changed from before Election Day.
Does divided government help or hurt mortgage rates? ▸
Bond markets often view divided government favorably because it lowers the odds of large new spending packages or abrupt policy swings, which can ease upward pressure on the Treasury yields mortgage rates track. Inflation and Fed decisions still matter more.
Will the 2026 election change housing policy in the Treasure Valley? ▸
It is not expected to. Idaho remains solidly Republican at the state level, so local land use, permitting and property tax policy in the Treasure Valley aren’t expected to shift because of the national result.
Should I wait until after the election to buy a home in Boise? ▸
The data doesn’t support waiting for the election to lower rates. Rates were essentially unchanged the week of the election and are higher than they were last summer, so today’s high 6s to low 7s range is a reasonable planning assumption.
Is the Treasure Valley a buyer’s or seller’s market right now? ▸
It is still a seller’s market by supply metrics, but buyers have more room to negotiate than a few years ago. Ada and Canyon counties ended the first half of 2026 with about 2.5 months of supply after new listings rose by double digits.
How fast are homes selling in Boise? ▸
Homes priced to the current market and shown well are still selling quickly, with Boise’s median days on market at roughly a week through the first half of 2026. Overpriced or dated listings are sitting longer and taking price cuts.
Could the Fed raise interest rates before the end of 2026? ▸
It’s possible. With inflation running around 3.7%, at least one analyst has flagged a possible Fed rate hike before year-end, so rates could move in either direction depending on upcoming inflation and jobs reports.
What should Treasure Valley buyers and sellers focus on heading into 2027? ▸
Local conditions: current mortgage rates, inventory in your price range and neighborhood, and your own timeline. Divided government makes fast, sweeping federal policy changes less likely, giving a reasonably stable backdrop to plan around.